“Clearly, sustained low inflation implies less uncertainty about the future, and lower risk premiums imply higher prices of stocks and other earning assets. We can see that in the inverse relationship exhibited by price/earnings ratios and the rate of inflation in the past. But how do we know when irrational exuberance has unduly escalated asset values, which then become subject to unexpected and prolonged contractions…”
Alan Greenspan (1926-2026)
Chairman of the Federal Reserve (1987-2006)
In the above quote, the recently deceased former “Maestro of the Markets” warned of “unexpected and prolonged contractions” that could result from too-high asset prices, correctly anticipating the dot-com bust. Unfortunately, this warning was given in 1996. The bull market lasted another three plus years and ultimately went up another 100+% before it peaked. There’s probably a lesson in that.
Today, the stock market is again on a tear, delivering its best quarterly gain in more than five years. Fueled by one of its strongest two-month periods ever, the market recovered from a 9% loss in reaction to the Iranian war in record time. Economically sensitive benchmarks such as small-cap and transportation stocks are off to their best start to the year since the recessionary bounce-back year of 1991. With company earnings soaring, the market’s rise is at least somewhat justified. Still, stocks remain historically expensive.[1]
The stock market has managed outsized gains this year despite elevated inflation readings that would typically weigh on valuations. Inflation is running above the Fed’s target rate, with the new chairman of the Federal Reserve now widely expected to raise rates, not lower them as assumed when he was nominated.
Other trends driving the market continued apace in Q2, with technology stocks leading the way. Surprisingly left out were energy stocks. Despite gangbuster earnings, they are now trading lower than before the Iranian war, even with the Strait of Hormuz not yet fully open.
Another noteworthy laggard this year is the software industry, with stock prices pummeled even though operating results (revenue and profits) remain strong. Software companies now trade at a discount to the broad market (forward P/E – as seen atop the following page) for the first time in 18 years.
The market is concerned that a) AI coding tools make it easier for companies to code their own software solutions and b) competition will intensify as upstarts build software products faster. We see the first as unlikely but the second as a very valid concern considering Anthropic recently said their engineers now ship 8x as much code per quarter than they did during the previous four years!
While the software industry, a former market darling, is getting shellacked, the new stars of the market are anything related to the massive, world-changing AI datacenter buildout. According to the Wall Street Journal, AI spending is behind half of all investment grade debt issued and 87% of all venture capital funding this year. Almost all the big winners in the stock market are related in some way to this trade. The poster child for the boom is no longer Nvidia but rather memory chip stocks, as modern AI applications require a lot of memory. Micron Technology, for example, was up a mere 242% in the second quarter. Fortunately, our stock portfolios have included exposure to some of the big winners. The trillion-dollar question is how long will the epic AI buildout last? Or perhaps, how long will the bottlenecks allowing insane pricing for those selling into it last?
The datacenter frenzy has also reached the IPO market. SpaceX just completed the largest IPO ever, partially on the promise of someday putting AI datacenters in space, where the sun always shines and no pesky neighbors complain.
We’ve never seen an IPO capture the popular imagination of investors like this one. Perhaps it’s no wonder that SpaceX came public at a value equivalent to that of all combined IPOs that occurred during the past decade.
SpaceX has so far followed a common pattern with IPOs: an initial pop followed by a pullback, with SpaceX having already traded below its first day trading price (but not below its issuance price).
We have fielded many questions about this IPO and have mostly emphasized three thoughts:
1) SpaceX is extremely expensive at 40x sales, the highest multiple among S&P 500 companies. To be clear, that is 40x next year’s estimated The IPO multiple of price to actual prior year sales was much higher at 98x.
2) Despite its lofty valuation, we don’t really know where SpaceX stock is headed. Tesla exemplifies this, showing stocks can be expensive… and stay that way while continuing to reward investors. Still, in all cases, we believe high valuation brings heightened risk of permanent capital impairment.
3) IPOs tend not to be the best investment candidates (blockbusters like Google are the exception, not the rule).[2]
The recent pullback in SpaceX stock is not all that surprising. Ninety percent of IPOs trade below their issuance price within their first year of trading[3] and it’s easy to see why this happens. Today, anyone can buy SpaceX… but not everyone can sell. Insiders (who own most of the stock) have limited ability to sell shares[4]… for now. Over the next year, they, and many other investors currently restricted, will be able to sell their shares.
Not to be outdone, AI all-stars OpenAI and Anthropic are poised to go public this year, potentially also at trillion-dollar valuations. Even adjusting for inflation, this year’s big three IPOs are projected to be among the largest of all time. The value of SpaceX, OpenAI and Anthropic once public, may reach nearly $4 trillion dollars. This would exceed the value of all IPOs during the heady dot-com period of 1995-2000, even accounting for inflation by converting to 2026 dollars.
Companies largely decide when to go public and it says something about the state of the market that they are choosing to sell now. While today’s new tech companies are much more profitable than those of the dot-com days, we can’t help but recall yesteryear’s internet darling IPOs that lost most of their value during an ensuing three-year equity bear market.
Tech stocks are racing to new highs and some private companies clearly think it is a great time to sell. Yet, private equity firms mostly remain unable or unwilling to unload their portfolio companies. Some 70% of portfolio company exits are being offloaded from one private equity firm to another, with the remainder sold to corporate buyers and almost none through IPO exits. Many of these funds are being weighed down by their significant exposure to software companies that the market now hates. Still, we wonder what else may be lurking beneath the surface and whether the halcyon decades of stellar private equity returns have come to an end.
You would think private equity firms would happily sell their portfolio companies into a stock market that, by almost any measure, is as expensive as it has ever been. The below-left chart shows across-the-board stretched stock market valuation. One of these valuation measures, the CAPE (cyclically adjusted Price/Earnings ratio, otherwise known as the Shiller P/E), compares today’s price to the past ten years of inflation-adjusted earnings for the S&P 500 Index. Today’s CAPE valuation was surpassed only briefly during the dot-com tech bubble.
In the past, the CAPE has done a good job predicting market returns to come (lower valuation = higher forward 10-year returns)… until recently. Through much of the 2010s, the market looked expensive by historical standards, yet returns from those levels were still strong. Why has the stock market continued to power forward in recent years despite record high valuations?
A likely answer is profitability. How expensive a stock deserves to be of course depends partly on how profitable the company is. Return on equity (ROE) is one measure of corporate profitability. In recent years, ROE has been running off-the-chart high, driven by the dominance of large U.S. tec h companies.[5] That has helped support structurally higher valuations.
Higher profitability has also fueled earnings growth. This year has seen the best earnings growth since COVID, with the S&P 500 forward P/E ratio actually declining despite the index rising more than 10% year-to-date. Similarly, even after rising 30% since late March, the Nasdaq Composite now trades at 25x forward earnings, below its five-year average valuation!
In most years, earnings forecasts start out too optimistic and are steadily revised down as more information becomes available. Earnings expectations for 2026 and especially 2027 are anomalies, as they have been steadily revised up.
Companies in the S&P 500 are expected to report a 22% jump in second-quarter profits and see 23% growth for the full year, according to FactSet. With earnings growth expected to remain robust, today’s high valuation is easier to understand.
We are willing to accept that today’s optically expensive market may not be as risky as similarly expensive markets were in the past given today’s enhanced profitability and earnings growth. With that said, there are limits to our willingness to relax valuation constraints. An unprecedented one-third of S&P 500 Index market capitalization trades at more than 10x revenue.
Seeing all these companies trading for more than 10x revenues reminds us of something the CEO of Sun Microsystems said in 2002, reflecting on the dot-com era:
“Two years ago, we were selling at 10 times revenues when we were at $64. At 10 times revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes you pay no taxes on your dividends, which is kind of illegal. And that assumes with zero R&D for the next 10 years, I can maintain the current revenue run rate. Now, having done that, would any of you like to buy my stock at $64? Do you realize how ridiculous those basic assumptions are? You don’t need any transparency. You don’t need any footnotes. What were you thinking?”
While there are always exceptions, the history of paying 10 times sales or more for stocks shows very poor returns (barely keeping up with bonds – as measured by the Barclays Bloomberg U.S. Aggregate bond market index in red below).
We will always seek to avoid “irrational exuberance” and excessive valuations, knowing the good times don’t always last… but 2026 is so far a good reminder of why, no matter the situation, we never recommend being completely out of the stock market.
It is also important to be mindful that good things are happening. Despite currently elevated inflation readings, today’s massive buildout of AI should be deflationary in the long run. It is a technology that allows people to do more with less. It is making us more productive, and productivity is one of the most fundamental drivers of economic growth.
We look forward to all the inevitable economic progress as we steward your portfolios alongside ours.
Thank you for your continued trust and support.
Sincerely,
John G. Prichard Kurt Beimfohr Miles E. Yourman
Past performance is not indicative of future results. The above information is based on internal research derived from various sources and does not purport to be a statement of all material facts relating to the information and markets mentioned. It should not be construed that the information in this commentary is a recommendation to purchase or sell any securities.
[1] Indeed, the central lesson of our opening quote is probably that “being expensive” does not mean something will go down in the near-term… or ever. Even after the dot-com crash, the market never dropped to the level at the time of Greenspan’s warning.
[2] A recent study by Jay Ritter of the University of Florida showed the average return for an IPO purchased at the end of its first day of trading lagged the market by 21% over the subsequent three years. This research covers nearly 9,300 IPOs during 1980 to 2024.
[3] From the book “The Lifecycle Trade: How to Win at Trading IPOs and Super Growth Stocks” by Eve Boboch, Kathy Donnelly, Eric Krull and Kurt Daill.
[4] To be fair, insiders already had plenty of chances to sell SpaceX shares pre-IPO in private markets. On the other hand, while they could sell, it was not at today’s post-IPO higher valuation, which might change their thinking when lockups expire.
[5] Per Goldman Sachs: the collective ROE of the seven largest tech stocks is 44%, expanding 9% over the past three years while the median S&P 500 company ROE has declined.

Summer 2026 Quarterly Commentary
July 13th, 2026
“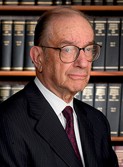 Clearly, sustained low inflation implies less uncertainty about the future, and lower risk premiums imply higher prices of stocks and other earning assets. We can see that in the inverse relationship exhibited by price/earnings ratios and the rate of inflation in the past. But how do we know when irrational exuberance has unduly escalated asset values, which then become subject to unexpected and prolonged contractions…”
Alan Greenspan (1926-2026)
Chairman of the Federal Reserve (1987-2006)
In the above quote, the recently deceased former “Maestro of the Markets” warned of “unexpected and prolonged contractions” that could result from too-high asset prices, correctly anticipating the dot-com bust. Unfortunately, this warning was given in 1996. The bull market lasted another three plus years and ultimately went up another 100+% before it peaked. There’s probably a lesson in that.
Today, the stock market is again on a tear, delivering its best quarterly gain in more than five years. Fueled by one of its strongest two-month periods ever, the market recovered from a 9% loss in reaction to the Iranian war in record time. Economically sensitive benchmarks such as small-cap and transportation stocks are off to their best start to the year since the recessionary bounce-back year of 1991. With company earnings soaring, the market’s rise is at least somewhat justified. Still, stocks remain historically expensive.[1]
The stock market has managed outsized gains this year despite elevated inflation readings that would typically weigh on valuations. Inflation is running above the Fed’s target rate, with the new chairman of the Federal Reserve now widely expected to raise rates, not lower them as assumed when he was nominated.
Other trends driving the market continued apace in Q2, with technology stocks leading the way. Surprisingly left out were energy stocks. Despite gangbuster earnings, they are now trading lower than before the Iranian war, even with the Strait of Hormuz not yet fully open.
Another noteworthy laggard this year is the software industry, with stock prices pummeled even though operating results (revenue and profits) remain strong. Software companies now trade at a discount to the broad market (forward P/E – as seen atop the following page) for the first time in 18 years.
The market is concerned that a) AI coding tools make it easier for companies to code their own software solutions and b) competition will intensify as upstarts build software products faster. We see the first as unlikely but the second as a very valid concern considering Anthropic recently said their engineers now ship 8x as much code per quarter than they did during the previous four years!
While the software industry, a former market darling, is getting shellacked, the new stars of the market are anything related to the massive, world-changing AI datacenter buildout. According to the Wall Street Journal, AI spending is behind half of all investment grade debt issued and 87% of all venture capital funding this year. Almost all the big winners in the stock market are related in some way to this trade. The poster child for the boom is no longer Nvidia but rather memory chip stocks, as modern AI applications require a lot of memory. Micron Technology, for example, was up a mere 242% in the second quarter. Fortunately, our stock portfolios have included exposure to some of the big winners. The trillion-dollar question is how long will the epic AI buildout last? Or perhaps, how long will the bottlenecks allowing insane pricing for those selling into it last?
The datacenter frenzy has also reached the IPO market. SpaceX just completed the largest IPO ever, partially on the promise of someday putting AI datacenters in space, where the sun always shines and no pesky neighbors complain.
We’ve never seen an IPO capture the popular imagination of investors like this one. Perhaps it’s no wonder that SpaceX came public at a value equivalent to that of all combined IPOs that occurred during the past decade.
SpaceX has so far followed a common pattern with IPOs: an initial pop followed by a pullback, with SpaceX having already traded below its first day trading price (but not below its issuance price).
We have fielded many questions about this IPO and have mostly emphasized three thoughts:
1) SpaceX is extremely expensive at 40x sales, the highest multiple among S&P 500 companies. To be clear, that is 40x next year’s estimated The IPO multiple of price to actual prior year sales was much higher at 98x.
2) Despite its lofty valuation, we don’t really know where SpaceX stock is headed. Tesla exemplifies this, showing stocks can be expensive… and stay that way while continuing to reward investors. Still, in all cases, we believe high valuation brings heightened risk of permanent capital impairment.
3) IPOs tend not to be the best investment candidates (blockbusters like Google are the exception, not the rule).[2]
The recent pullback in SpaceX stock is not all that surprising. Ninety percent of IPOs trade below their issuance price within their first year of trading[3] and it’s easy to see why this happens. Today, anyone can buy SpaceX… but not everyone can sell. Insiders (who own most of the stock) have limited ability to sell shares[4]… for now. Over the next year, they, and many other investors currently restricted, will be able to sell their shares.
Not to be outdone, AI all-stars OpenAI and Anthropic are poised to go public this year, potentially also at trillion-dollar valuations. Even adjusting for inflation, this year’s big three IPOs are projected to be among the largest of all time. The value of SpaceX, OpenAI and Anthropic once public, may reach nearly $4 trillion dollars. This would exceed the value of all IPOs during the heady dot-com period of 1995-2000, even accounting for inflation by converting to 2026 dollars.
Companies largely decide when to go public and it says something about the state of the market that they are choosing to sell now. While today’s new tech companies are much more profitable than those of the dot-com days, we can’t help but recall yesteryear’s internet darling IPOs that lost most of their value during an ensuing three-year equity bear market.
Tech stocks are racing to new highs and some private companies clearly think it is a great time to sell. Yet, private equity firms mostly remain unable or unwilling to unload their portfolio companies. Some 70% of portfolio company exits are being offloaded from one private equity firm to another, with the remainder sold to corporate buyers and almost none through IPO exits. Many of these funds are being weighed down by their significant exposure to software companies that the market now hates. Still, we wonder what else may be lurking beneath the surface and whether the halcyon decades of stellar private equity returns have come to an end.
You would think private equity firms would happily sell their portfolio companies into a stock market that, by almost any measure, is as expensive as it has ever been. The below-left chart shows across-the-board stretched stock market valuation. One of these valuation measures, the CAPE (cyclically adjusted Price/Earnings ratio, otherwise known as the Shiller P/E), compares today’s price to the past ten years of inflation-adjusted earnings for the S&P 500 Index. Today’s CAPE valuation was surpassed only briefly during the dot-com tech bubble.
In the past, the CAPE has done a good job predicting market returns to come (lower valuation = higher forward 10-year returns)… until recently. Through much of the 2010s, the market looked expensive by historical standards, yet returns from those levels were still strong. Why has the stock market continued to power forward in recent years despite record high valuations?
A likely answer is profitability. How expensive a stock deserves to be of course depends partly on how profitable the company is. Return on equity (ROE) is one measure of corporate profitability. In recent years, ROE has been running off-the-chart high, driven by the dominance of large U.S. tec h companies.[5] That has helped support structurally higher valuations.
Higher profitability has also fueled earnings growth. This year has seen the best earnings growth since COVID, with the S&P 500 forward P/E ratio actually declining despite the index rising more than 10% year-to-date. Similarly, even after rising 30% since late March, the Nasdaq Composite now trades at 25x forward earnings, below its five-year average valuation!
In most years, earnings forecasts start out too optimistic and are steadily revised down as more information becomes available. Earnings expectations for 2026 and especially 2027 are anomalies, as they have been steadily revised up.
Companies in the S&P 500 are expected to report a 22% jump in second-quarter profits and see 23% growth for the full year, according to FactSet. With earnings growth expected to remain robust, today’s high valuation is easier to understand.
We are willing to accept that today’s optically expensive market may not be as risky as similarly expensive markets were in the past given today’s enhanced profitability and earnings growth. With that said, there are limits to our willingness to relax valuation constraints. An unprecedented one-third of S&P 500 Index market capitalization trades at more than 10x revenue.
Seeing all these companies trading for more than 10x revenues reminds us of something the CEO of Sun Microsystems said in 2002, reflecting on the dot-com era:
“Two years ago, we were selling at 10 times revenues when we were at $64. At 10 times revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes you pay no taxes on your dividends, which is kind of illegal. And that assumes with zero R&D for the next 10 years, I can maintain the current revenue run rate. Now, having done that, would any of you like to buy my stock at $64? Do you realize how ridiculous those basic assumptions are? You don’t need any transparency. You don’t need any footnotes. What were you thinking?”
While there are always exceptions, the history of paying 10 times sales or more for stocks shows very poor returns (barely keeping up with bonds – as measured by the Barclays Bloomberg U.S. Aggregate bond market index in red below).
We will always seek to avoid “irrational exuberance” and excessive valuations, knowing the good times don’t always last… but 2026 is so far a good reminder of why, no matter the situation, we never recommend being completely out of the stock market.
It is also important to be mindful that good things are happening. Despite currently elevated inflation readings, today’s massive buildout of AI should be deflationary in the long run. It is a technology that allows people to do more with less. It is making us more productive, and productivity is one of the most fundamental drivers of economic growth.
We look forward to all the inevitable economic progress as we steward your portfolios alongside ours.
Thank you for your continued trust and support.
Sincerely,
John G. Prichard Kurt Beimfohr Miles E. Yourman
Past performance is not indicative of future results. The above information is based on internal research derived from various sources and does not purport to be a statement of all material facts relating to the information and markets mentioned. It should not be construed that the information in this commentary is a recommendation to purchase or sell any securities.
[1] Indeed, the central lesson of our opening quote is probably that “being expensive” does not mean something will go down in the near-term… or ever. Even after the dot-com crash, the market never dropped to the level at the time of Greenspan’s warning.
[2] A recent study by Jay Ritter of the University of Florida showed the average return for an IPO purchased at the end of its first day of trading lagged the market by 21% over the subsequent three years. This research covers nearly 9,300 IPOs during 1980 to 2024.
[3] From the book “The Lifecycle Trade: How to Win at Trading IPOs and Super Growth Stocks” by Eve Boboch, Kathy Donnelly, Eric Krull and Kurt Daill.
[4] To be fair, insiders already had plenty of chances to sell SpaceX shares pre-IPO in private markets. On the other hand, while they could sell, it was not at today’s post-IPO higher valuation, which might change their thinking when lockups expire.
[5] Per Goldman Sachs: the collective ROE of the seven largest tech stocks is 44%, expanding 9% over the past three years while the median S&P 500 company ROE has declined.